

Jewett-Cameron Trading company (NASDAQ: JCTC) is a tiny nanocap stock (current market cap is $14.7 million) based outside of Portland, OR. The company offers lawn, garden and pet related products. Jewett-Cameron started out as a lumber wholesaler in 1953 and more recently has tried diversifying its product lines into lawn, garden, and pet products to reduce exposure to the home construction industry. Jewett-Cameron is a classic net, net “cigar butt” type investment, with meager growth prospects. However, at current prices Jewett-Cameron offers good value with limited downside risk given the stock trades close to its estimated liquidation value and at discount to its net current asset value (current assets – total liabilities).
Sale of Owned Real Estate Could Provide Catalyst for Stock Price
Jewett-Cameron closed its seed processing division in 2023 and is in the process of winding down the operation having sold most of the seed inventory and equipment. The company owns its seed processing facility outright which is in North Plains, OR. The combined size of the buildings is 109,500 square feet and the property is located on 11.6 acres. The property is listed at its $566,022 carrying value on the company’s balance sheet. Per Jewett-Cameron’s 2024 annual report, the property was listed for $9,000,000 in July 2024. I have no idea what the property is worth in the current environment and for this analysis I will be conservative in putting an estimated value on the seed processing facility. Let’s just call it 50%, or $4,500,000. Back in 2022, former Jewett-Cameron CFO estimated the value of the property to be $4.8 million.
Net Current Asset Valuation and Liquidation Analysis
Below you can see Jewett-Cameron’s balance sheet for the quarter ending November 30th, 2024.
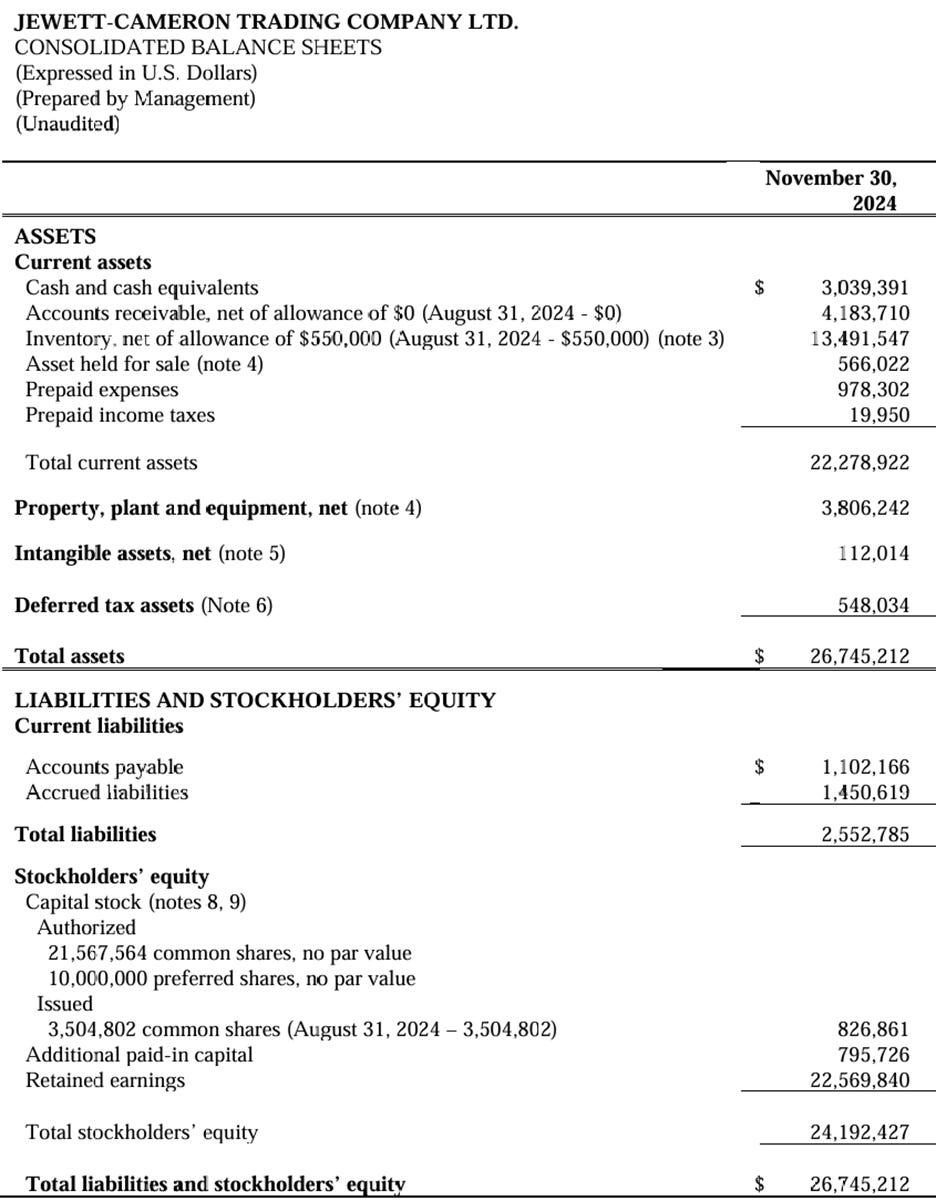
As you can see, current assets are about $22.2 million and total liabilities are roughly $2.5 million. With 3,504,802 shares outstanding, that leaves Jewett-Cameron with a net current asset value of $5.63, which represents about 34% upside from the closing price of $4.20 as of market close on April 5th, 2025.
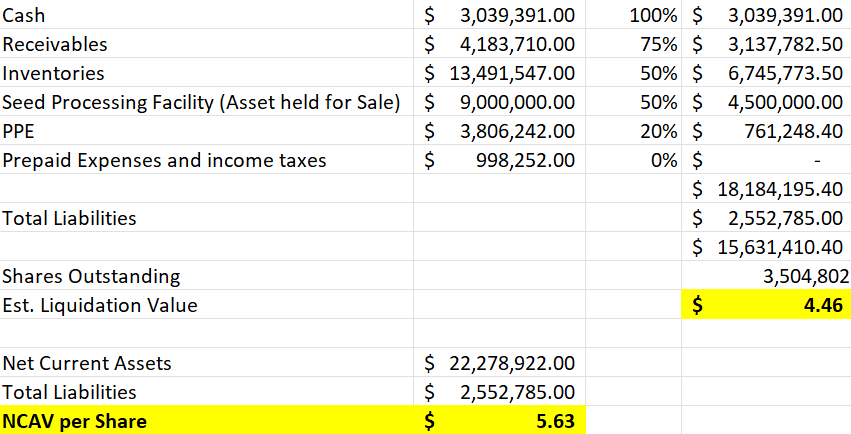
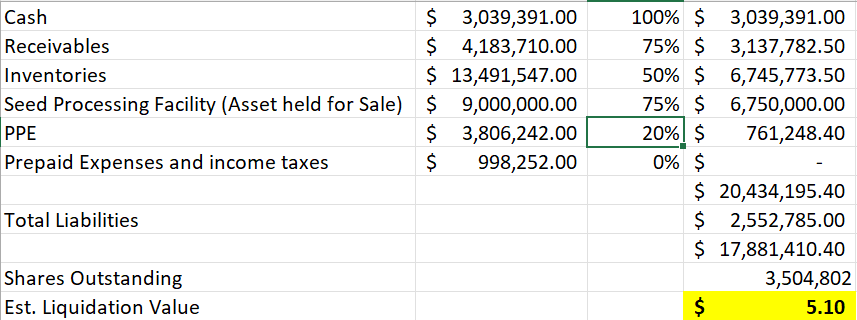
For the liquidation analysis, I assumed receivables and inventories to be discounted by 25% and 50%, respectively. I assumed property, plant and equipment to be worth only 20% of book value, which is very conservative, and the valuation is likely to be higher than this. As you can see from the figure above, even if Jewett-Cameron was only able to get 50% of the $9 million list price for the seed processing facility, the liquidation value is $4.46, which is higher than the current stock price. If the company could get 75% of list price, then the liquidation value is roughly $5.10, which represents 21% upside from the current price of $4.20.
Risks
As previously mentioned, Jewett-Cameron is not a high growth business and is currently losing money. For the most recent quarter ending November 2024, the company reported an operating loss of $858,000. The stock is also small (current $14.7 million market cap) with low trading volume so limit orders should be used when buying or selling the stock. Given the current economic environment with high-interest rates and recently announced tariffs, Jewett-Cameron’s operating results and profitability could be adversely affected for some time.
Conclusion
Jewett-Cameron has had positive earnings per share in 9 out of the last 10 years, having only shown a loss of $0.01 for the year ending August 2023 (Jewett-Cameron reports their fiscal year end in August). Moreover, Jewett-Cameron’s average annual operating income (EBIT) over the last 10 years has been roughly $2.6 million. At a current enterprise value of $12.45 million, that equates to a roughly 4.79 EV to average “normalized” EBIT. Jewett-Cameron has also repurchased quite a bit of its stock over the previous 10 years. From 2015 - 2024, JCTC’s share count has declined about 4% annually. There is a potential catalyst that could substantially move the stock price if Jewett-Cameron is able to sell their seed processing facility at anything close to the listed value. Even if they aren’t able to sell it, the stock’s discount to net current asset value should provide some margin of safety for investors.
Full Disclosure: I currently own shares of JCTC and the stock makes up 2.75% of my portfolio.
Take a look at my Substack at terryschumacher.substack.com to see a decidedly different perspective about Jewett-Cameron. Despite having some property listed for sale at $9 million (my estimate is it's worth $5.3 million), they are failing as an operating company, and the three articles I have posted on the company explain why. I consider myself to be an expert on the company having been a sell-side security analyst for 10 years, but more importantly I was CFO of Jewett-Cameron from 2007 to 2009 and have followed the company very closely ever since then.
Hi Nick, thanks for the great write up! I saw you mentioned "Jewett-Cameron closed its seed processing division in 2023 and is in the process of winding down the operation" and was wondering if there are signs of shareholder dissatisfaction or prior investor unrest that might indicate frustration with management's pace in realizing value from the seed processing facility sale or overall capital allocation.