

I have recently had my eye on two real estate companies currently in the process of liquidation. These “event-driven” investments are less correlated to the overall market, and I believe offer an attractive risk adjusted rate of return.
First, I’ll share an update on Seritage Growth Properties that I wrote up back in late April.
Seritage Growth Properties: Trading at a Discount to Liquidation Value

Seritage Growth Properties (NYSE: SRG) has been aggressively selling properties and paying down debt over the last four years since they announced a liquidation in order to maximize value for shareholders.
Since my writeup, Seritage was able to refinance a $50 million loan and reduce their overall debt load. Seritage also announced a sale of their Dallas property for $50.76 million.
What is now left is a portfolio of properties that I believe are worth much more than the market price with only about $15 million of debt based on my estimations. For the sake of being conservative, I will assume that all of Seritage Growth’s properties are valued at my initial bear case. Here are the property values I had assumed under a bear case.
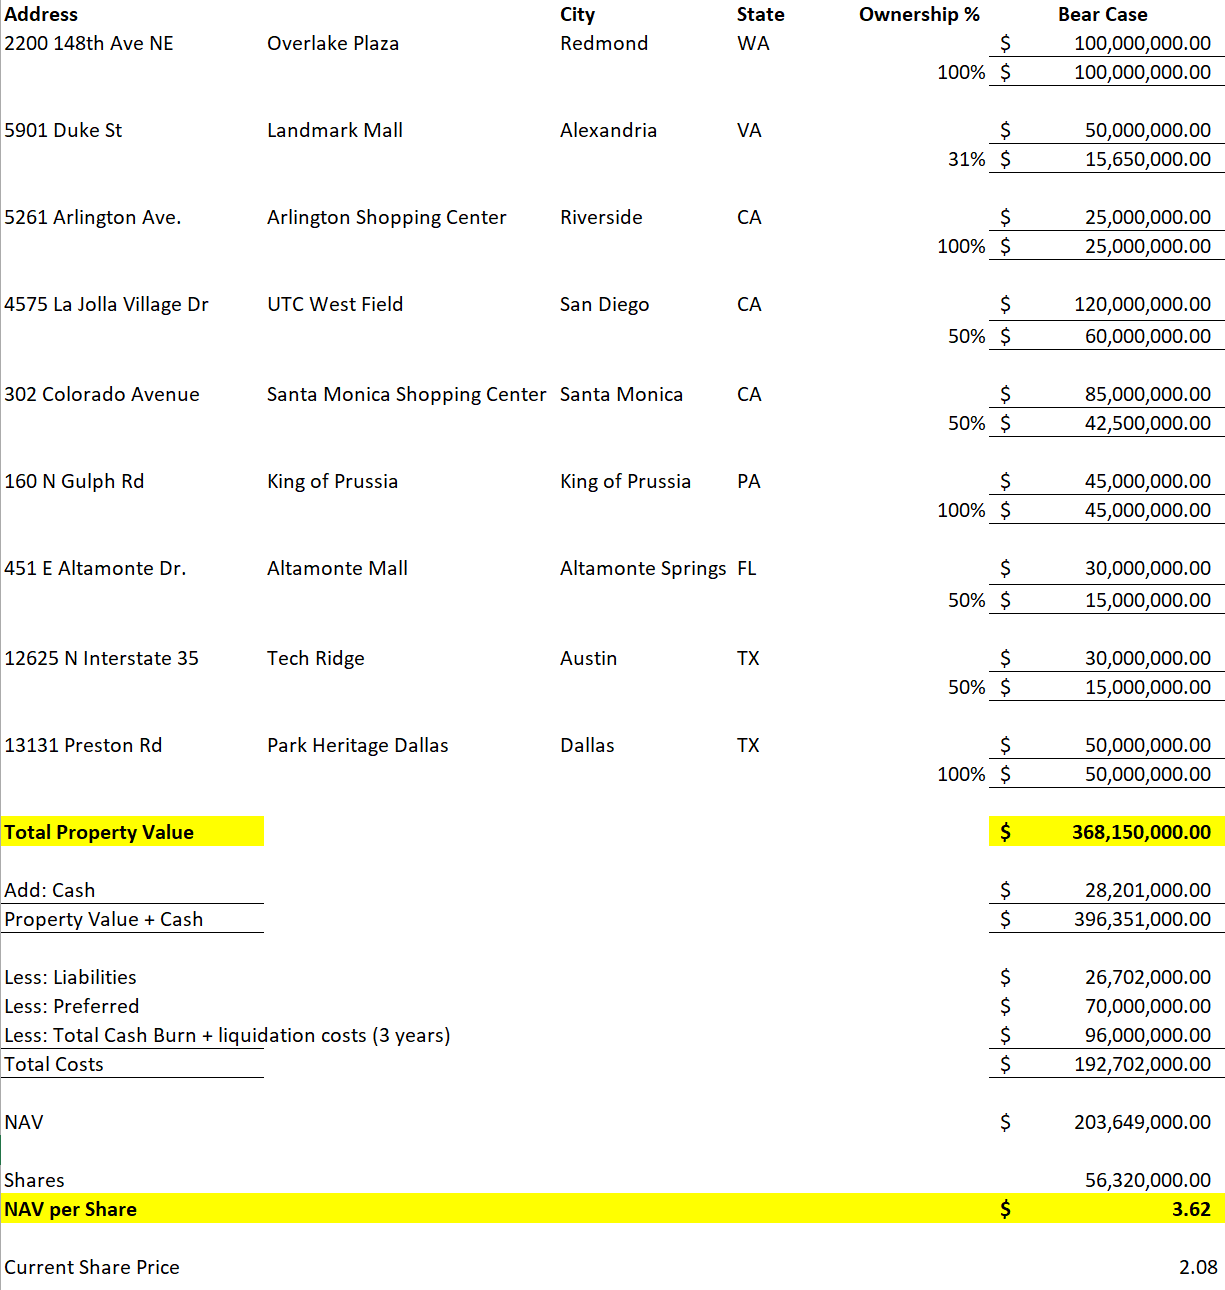
Even under a bear case scenario and including deductions for the preferred shares and total cash burn plus liquidation costs, I still get an estimated liquidation value of about $3.62. This assumes full liquidation takes 3 years. $3.62 represents about 70% of book value and 74% upside from the current share price of $2.08. If the liquidation happens in 3 years, my base case IRR is about 20% from the current share price. I could obviously be wrong on timing and the ultimate liquidation value but there seems to be adequate balance sheet value to protect both the preferred and common stock.
Seritage’s preferred stock has a large margin of safety because the conservative net asset value less all liabilities covers the preferred more than 5 times over. The preferred shares currently trade at roughly $22 per share, are continuously callable at $25, and the current yield is roughly 7.9%.
Next, I’ll also take a look at SITE Centers (SITC), a retail REIT in the process of liquidating that appears to trade at a meaningful discount to my estimate of liquidation value.
