

The Opportunity
Indianapolis based Hurco (HURC) designs and sells computerized machine tools and is currently selling at a discount to its net current asset value. Insiders have been buying the stock which is a great sign for investors since the management team has “skin in the game.”
The most recent 3rd quarter report was not pretty as sales declined roughly 20% from Q3 2023 to Q3 2024 as shown in the table below.

Hurco Companies Investor Website: SEC 10-Q
On a positive note, new orders increased 26% from Q3 2023 to Q3 2024.

Stocks selling for less than net current asset value often look ugly as is the case with Hurco. The stock has declined roughly 33% from its 52-week high around $28. The company has seen a slowdown in sales and recently cut its dividend. However, the stock now trades at a significant discount to net current asset value, offering value investors a rare opportunity in today’s pricey market.
From Chapter 43 of Security Analysis:
“Stocks selling below liquidation value are in many cases too cheap and so offer an attractive medium for purchase. We have thus a profitable field here for the technique of security analysis”
In Security Analysis, Ben Graham mentions that the net current asset value can be thought of as a rough approximation for the liquidation value for a company, meaning the value stockholders would receive if the company’s assets were sold and all the liabilities were paid off. Accounts receivable, inventories, and other current assets would be discounted in a hypothetical liquidation, so Graham suggested buying these stocks at substantial discount to the net current asset value to ensure a margin of safety.
Hurco is not exactly an exciting stock that is building sophisticated AI models or quickly growing revenues which is likely why it has fallen under the radar. Hurco designs and sells computerized machine tools used for creating tools, parts, etc. - which is not a high growth industry. Even in a normal economic environment, Hurco’s business does not generate high returns on invested capital (and recently cut its dividend) which is another reason the stock has sold off. That being said, the company is a legit micro-cap (with sustainable business operations) that was previously profitable. From 2014 - 2023, earnings per share averaged $1.67 (~11x Price / Earnings from the current price level of $18.72 as of September 19th) and Hurco only had one year (2020) from 2014 - 2023 where it showed a deficit in earnings. Hurco’s most recent annualized dividend was $0.64 (3.4% implied yield) and the company paid a dividend every year from 2014 - 2023. Moreover, Hurco’s share count has not increased over the last 10 years. (which is a good sign since it means your ownership stake isn’t being diluted as a common stockholder)
Valuation
For this valuation analysis, I am only going to do an asset-based valuation showing the net current asset value for Hurco since the company is not currently profitable. For some historical prospective, Hurco generated an average EPS of $2.45 (less than 8x PE from current price levels) from the years 2014 - 2019. This should give investors an idea of Hurco’s potential earning power if they can right the ship and restore profitability.
Here is a breakdown of Hurco’s current balance sheet based on the most recent quarter:
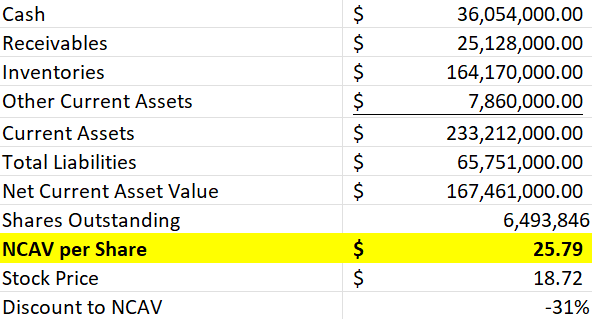
Hurco stock is currently trading at a 31% discount to net current asset value. Clearly the stock is cheap from an asset valuation standpoint. This makes sense since Hurco is in a low-growth, capitally intensive industry and does not have a leading market share. However, sometimes stocks get so cheap that they can still offer investors high annualized rates of return. Most of the downside risk is priced into Hurco’s stock and it seems at the current price level that there is more upside than downside.
What are the Insiders Doing?
Insider buying is a good sign especially for a stock trading at a discount to net current asset value. Investors face the problem of information asymmetry meaning insiders know more about what’s going on inside the company than investors do. Insider buying is a positive signal. When insiders own stock their incentives are aligned with stockholders, and they usually would not be buying stock in a “sinking ship.” It often means they believe the stock is undervalued and that they can restore the enterprise to profitability. In July, the CFO and other insiders acquired 2,915 shares at prices around $15. Not a lot, but still a good sign. As of the most recent proxy filing in January 2024, executive officers and directors owned roughly 7% of the stock.
Takeaway
At current price levels, I think Hurco offers value investors a compelling opportunity. The stock has issues and has seen a big slowdown in sales, but new orders are growing, and it seems more likely than not that the company can return to its prior days, where it was a consistently profitable enterprise that paid a consistent dividend. No guarantees here and there is the risk that Hurco is unable to right the ship and continues losing money. I think it’s prudent for investors to diversify their portfolio with a nice little basket of stocks selling for less than net current asset value.
Full disclosure, I currently own Hurco shares which make up roughly 2% of my portfolio.