

Based in Jacksonville, FL, Proficient Auto Logistics (NASDAQ: PAL) is a specialized trucking and logistics company primarily focused on transporting new and used vehicles for automobile manufacturers, dealerships, ports, auctions, and other players in the automotive supply chain.
The company moves roughly 4 million vehicles annually and now has close to a 25% estimated market share after buying Hansen & Adkins. PAL serves 100% of the automotive OEMs in U.S. transport.
Since PAL is a newer company with a limited operating track record and limited analyst coverage, my goal is to provide a brief snapshot of PAL’s valuation and normalized earnings after their acquisition of Hansen & Adkins.
Overview
PAL is a relatively new public company. It completed its IPO in 2024 after being formed through the combination of five established auto-transport businesses. PAL’s strategy is to consolidate a fragmented vehicle-transportation industry and use greater scale, route density, and fleet utilization to improve the economics of the combined business.
The first two years as a public company have been rocky, with the shares down over 60%. PAL went public at approximately $15 per share, but weaker industry conditions, disappointing profitability, acquisition-related expenses, and concerns surrounding the company’s increasingly leveraged balance sheet have weighed heavily on the stock. Shares now trade around $5.30.
PAL recently acquired Hansen & Adkins, significantly expanding its fleet and making PAL the largest finished-vehicle transportation provider in North America, with an estimated 25% share of its addressable market.
At the current price, I believe investors may be placing too much emphasis on PAL’s depressed near-term earnings and not enough on the earnings power of the combined business. If management can successfully integrate Hansen & Adkins, improve fleet utilization, and capitalize on tightening industry capacity, PAL has the potential to generate substantially greater free cash flow than its recent results suggest. With the shares trading at what I estimate is a low-single-digit multiple of normalized free cash flow, I believe PAL is currently priced well below intrinsic value.
Recent Insider Buying and a CEO with a Successful Track Record
PAL’s CFO and COO along with a director have recently been buying stock in the company at the depressed prices, which is a good sign, and likely means they believe the shares to be undervalued.
As of the latest proxy filing, CEO Richard O’Dell owns roughly 3.6% of PAL shares. O’Dell was previously CEO of Saia, Inc. (NASDAQ: SAIA) from 2006 - 2020. Saia stock is up over 20x since 2006, so O’Dell has a successful track record of creating shareholder value and running a publicly traded freight and logistics company.
Recent M&A
Now that PAL has acquired Hansen & Adkins, PAL’s revenues are projected to be at least $800 million with roughly $61 million in EBITDA, or roughly a 7.3% EBITDA margin.
PAL is funding the Hansen & Adkins acquisition through a combination of cash on hand and additional debt financing. The $130 million upfront purchase price consists of approximately $75 million of assumed debt, $52 million of cash, and $3 million of PAL stock, implying a purchase multiple of roughly 4.8x H&A's trailing adjusted EBITDA, or approximately 3.9x including estimated synergies.
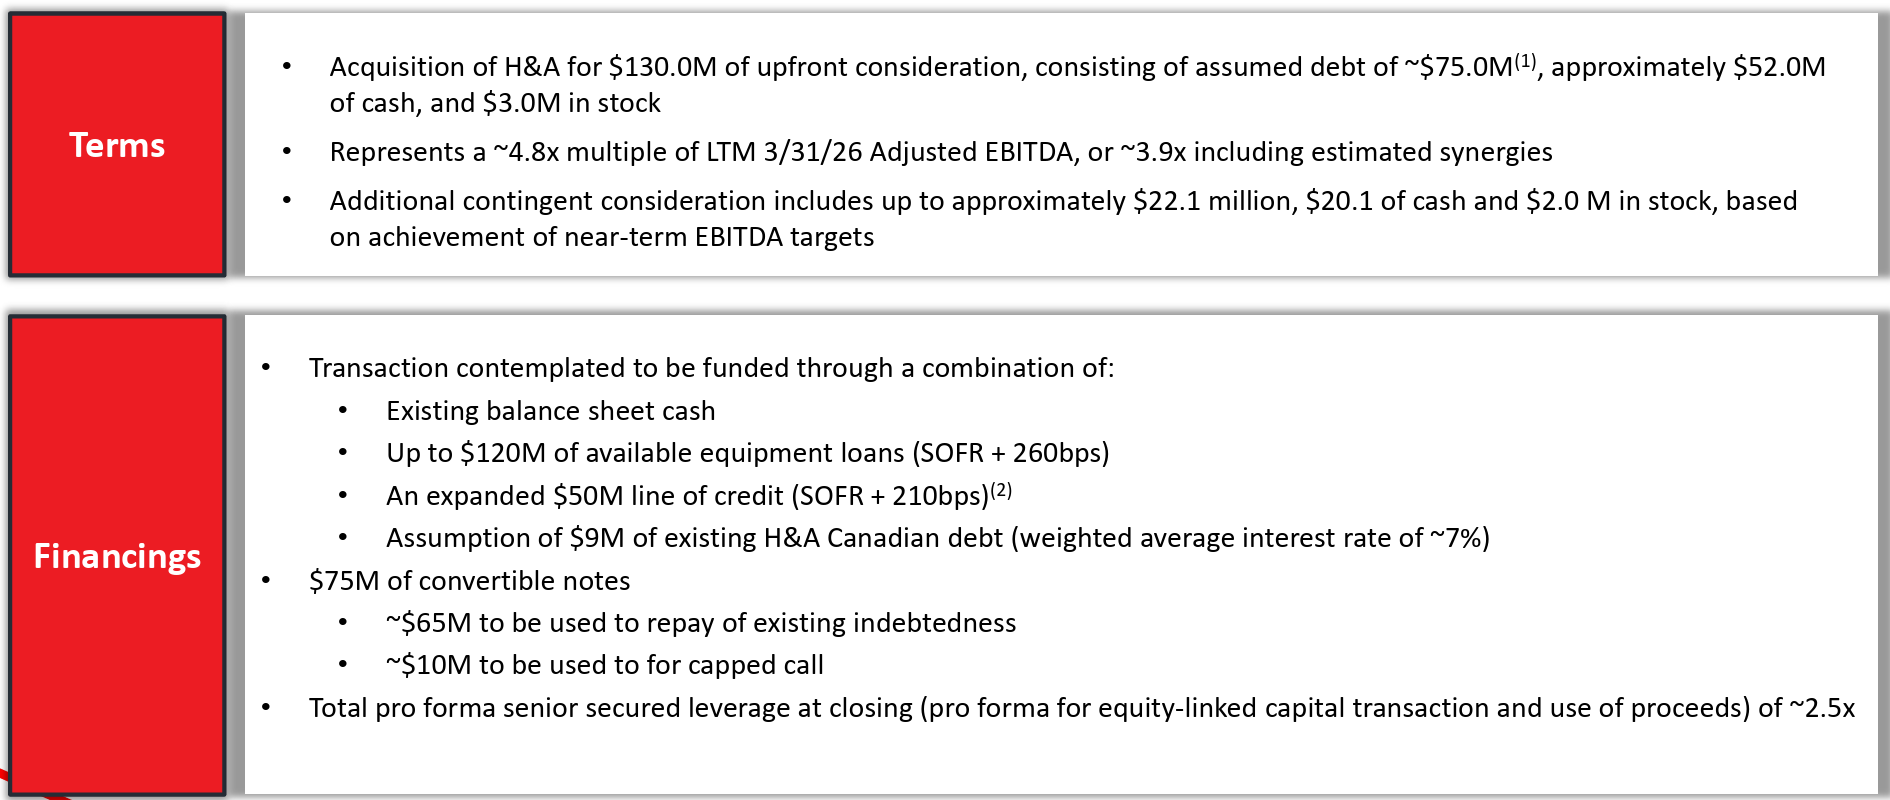
To fund the transaction and refinance existing obligations, PAL expanded its equipment financing capacity to as much as $120 million and increased its revolving credit facility to $50 million. The company also issued $75 million of 5.5% convertible notes, with approximately $65 million of the proceeds being used to repay existing indebtedness and another $10 million used to purchase a capped call designed to reduce potential shareholder dilution.
PAL expects pro forma senior secured leverage to be approximately 2.5x at closing. While the transaction increases the company's overall debt load, the relatively modest acquisition multiple and long-dated convertible financing make the capital structure manageable if the combined company can achieve management's expected earnings and synergy targets. An additional $22.1 million of contingent consideration could be paid if H&A reaches certain near-term EBITDA targets, although roughly $2 million of that amount would be paid in PAL stock.
At $5.30 per share, I believe the market is substantially undervaluing the earnings power of the combined business. Below, I estimate PAL’s normalized free cash flow, analyze its post-acquisition balance sheet, compare its valuation with publicly traded peers, and estimate the potential upside if management successfully integrates Hansen & Adkins.
