

Overview
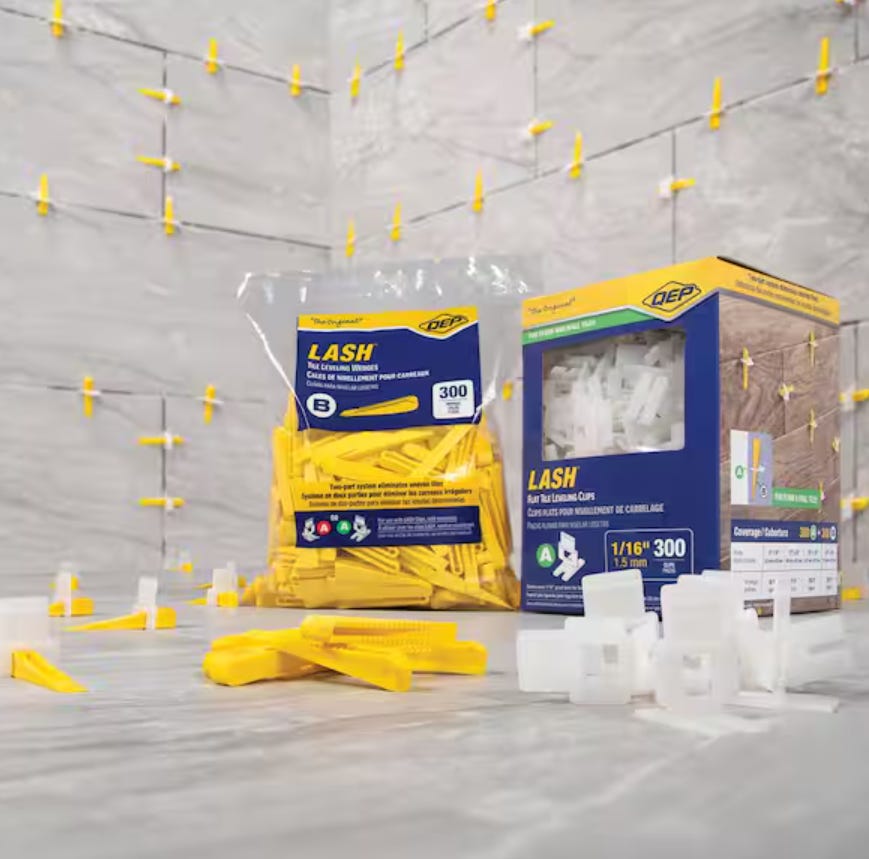
QEPC (OTCQX: QEP) manufactures and sells tile installation supplies and other flooring installation materials. QEP’s largest customer is Home Depot and QEP has been doing business with Home Depot for over 40 years. If you’ve ever done a tile project and bought supplies at Home Depot, you’ve likely heard of QEP. They make all the supplies needed for tile installation; everything from tile spacers, to trowels, to grout cleaning sponges and grout floats. QEP also makes tile nippers, leveling kits, and tile cutters. If you walk down the flooring aisle at a Home Depot, you’ll see the section with all the blue and yellow QEP products. QEP is based out of Boca Raton, FL and trades over the counter.
Management Has Recently Made Strategic Moves That Will Increase Long-Term Earning Power
QEP’s founder and chairman Lewis Gould (who currently owns nearly half of the company) recently handed over the reins to his son Leonard Gould and the company has recently been making some strategic divestitures that should unlock long-term value for shareholders. Recent decisions regarding capital allocation have been excellent and should provide substantial value for shareholders in the near-to-long term. QEP recently sold off a less profitable floor covering business and has been selling its international operations to simplify its operations and focus on its North American business. The company has also started paying a dividend of $0.20 per quarter, which would imply an annualized dividend of $0.80, or about a 2% yield at the current price of $39.
Recently, QEP has been working to simplify their operations by selling off their international units and a less profitable flooring covering business. QEP’s recent financial results have shown that these moves are creating substantial value for shareholders. QEP’s previous operating margins ((gross profit less operating expenses)/revenue)) were around 3%. Over the last three quarters, operating margins have nearly tripled to over 8.8%. Operating margins were roughly 10% for the most recent quarter ending in November 2024 and about 8.2% for the quarters ending in August and May 2024. Due to the strategic sales and increase in operating margins, it appears likely that QEP’s long-term earning power could more than triple. Prior to the sales of its international operations and floor covering business, QEP’s normalized earning power in any given year was roughly $1.70 per share. This is the average EPS from 2014 - 2023, not including two years where QEP posted a negative EPS. I believe QEP’s sustainable earning power is now likely closer to $5 per share. The market seems to have noticed, as QEP’s stock is up nearly 3x over the last two years. Despite the recent runup, I still believe QEP’s shares are undervalued.
Valuation
I am projecting QEP should earn roughly $22 million in operating income (EBIT) for 2024. Over the last three quarters, operating margins have averaged about 8.8%. Applying an 8.8% margin to the trailing twelve-month revenue of $249.073 million equals roughly $22 million in EBIT.

With no debt and about $34 million in cash, QEP’s enterprise value is currently about $92.8 million, implying a current EV to estimated 2025 EBIT of only 4.24.

I am estimating that QEP’s EBITDA for 2024 will be about $23.3 million, which would imply roughly 4x EV/EBITDA.
For the nine months ended November 30th, 2024, QEP earned $3.93 per share as you can see below.
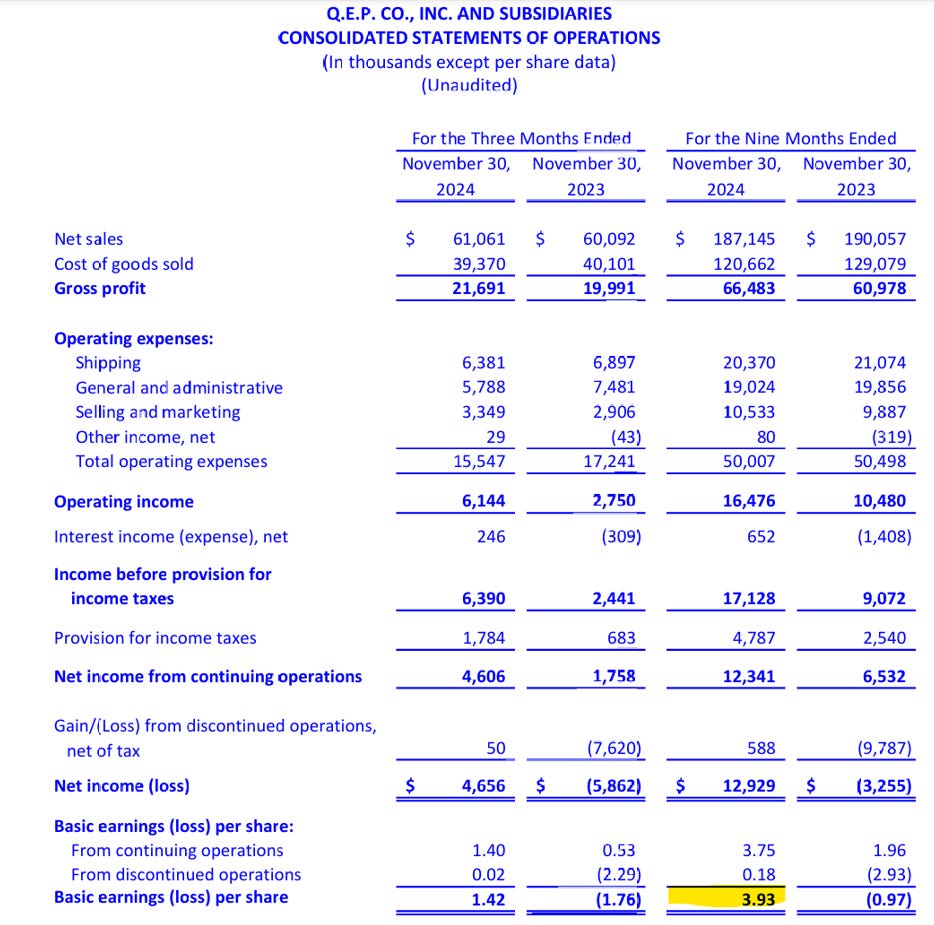
Annualizing this figure would imply about $5.24 per share in EPS for 2024 (3.93/3 = $1.31. 1.31 x 4 = $5.24). At the current price of $39, that would imply a price to earnings multiple of 7.4.
It should also be noted that QEP’s book value is currently $24.29 as of the most recent quarter. If QEP can earn something around $5 per share for 2024, that would imply a 20%+ return on equity ($5/$24.29). To find a company with a sustainable return on equity over 20% at a 7.4x PE multiple and 4x EV/EBITDA is rare and I believe QEP’s new “normalized earning power” will be at least $5 per share due to the strategic divestitures previously mentioned.
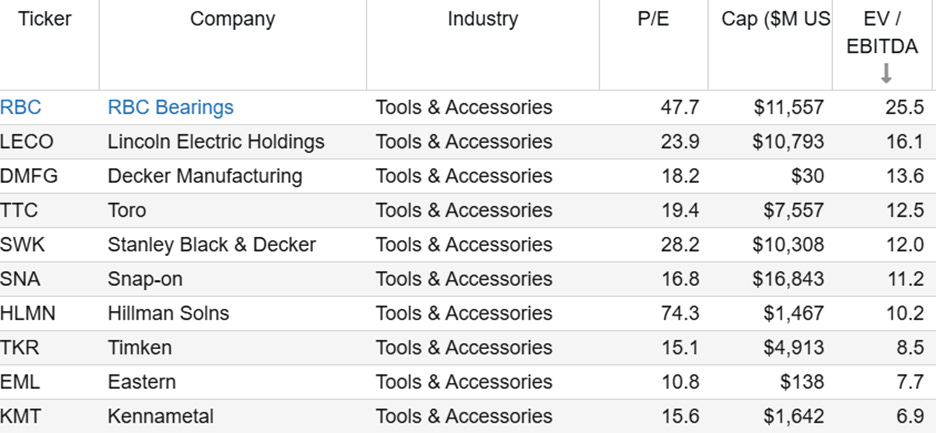
I ran a screener in Stock Rover to find comparable valuations in the “Tools & Accessories” industry. These peer companies obviously don’t offer the same products that QEP does, and their valuations are higher, but I think this screener should give a good snapshot of where valuations in the industry currently stand. The average EV/EBITDA multiple among these 10 companies is 12.4x. As previously mentioned, I am projecting QEP’s EV to 2025 EBITDA to be roughly 4x. So, you can see the large discount to average peer valuation multiples. Given that QEP is smaller than its peer group and has higher customer concentration risk (most of QEP’s sales are to Home Depot), I am going to apply a discount to the peer average to be conservative. Even if you only apply an 8 – 9x EV/EBITDA multiple on QEP, that would imply a fair value for QEP stock of $67 - $74 per share, or 72 – 90% upside from the current price of $39.

Risks and Takeaway
Probably the biggest risk with QEP stock is customer concentration. Sales to Home Depot account for roughly two-thirds of QEP’s total revenue. However, given that QEP has done business with Home Depot for over 40 years and has quality products and strong customer reviews, it doesn’t seem likely that Home Depot would want to hassle with trying to find another vendor to source tile installation tools. It should also be noted that QEP’s stock is small and is less liquid than larger companies that trade on the major exchanges. Limit orders should be used when buying the stock. Given QEP’s low earnings multiple, lack of debt and management’s focus on making smart capital allocation decisions, I think QEP offers strong upside potential with mitigated downside risk for patient investors.
I hold shares in QEP myself. I just wanted to say that you have some great posts on here.