

Back in April, I wrote about SiriusXM (NASDAQ: SIRI) and did a deep dive on the valuation of the company. SiriusXM just reported a solid 3rd quarter, and I just added to my position. SiriusXM stock now trades at just over 6x estimated 2025 free cash flow.
Price at time of original post on April 16th, 2025: $20.08
Current Price: $21.68
Dividends since original post: $0.54
Return: 10.7% (19.2% annualized)
Fast forward more than 6 months and the stock is up about 10.7% including dividends. My thesis was simple; you have a cash cow that the market hates and is dirt cheap trading at a 15% free cash flow yield. Moreover, SiriusXM currently pays a 5% dividend.
I wanted to revisit Sirius XM since they recently reported 3rd quarter earnings.
3rd Quarter Earnings Snapshot
Here are some of the highlights:
SiriusXM Q3 2025 Highlights
Revenue: $2.16 billion, down 1% year over year.
Net Income: $297 million — a major improvement from last year’s net loss due to the $3.36 billion Liberty Media goodwill impairment.
EPS: $0.84 vs. ($8.74) in Q3 2024.
Adjusted EBITDA: $676 million, slightly below last year’s $693 million.
EBITDA Margin: Solid at 31%, supported by disciplined cost control.
Self-Pay Monthly Churn: improved slightly year-over-year, to 1.6%
Operational & Strategic Commentary
CEO Jennifer Witz highlighted:
Better subscriber engagement
New content and deeper personalization
Continued innovation across the customer journey
Growth in digital advertising and podcasting
CFO Tom Barry emphasized:
Continued financial strength
A $120 million reduction in debt
$111 million returned to shareholders
Increased confidence leading to upgraded full-year guidance
Upgraded 2025 Guidance
SiriusXM raised expectations by $25 million across all key metrics:
Total Revenue: ~$8.525 billion
Adjusted EBITDA: ~$2.625 billion
Free Cash Flow: ~$1.225 billion
SiriusXM is now on track to generate about $1.3 billion in free cash flow for 2025 and I think it’s highly likely they do at least $1.5 billion by 2027.
That means Sirius XM will generate roughly $3.44 per share in free cash flow for 2025, which equates to a 15.8% free cash flow yield at the current price around $22. For 2027, I am projecting they will generate roughly $4.32 per share in free cash flow, which is nearly at 20% free cash flow yield!
Why Does the Market Hate SiriusXM? The Numbers Tell a Different Story
In my previous report on SiriusXM, I wrote that the prevailing view on Wall Street is that Sirius XM is a “melting ice cube” and a classic value trap, weighed down by slowing subscriber growth. Many analysts assume Spotify, Apple Music, and other streaming platforms will steadily erode the company’s market share. This narrative, combined with last year’s impairment charge—helped to explain why the stock sits near five-year lows.
Bottom line, the stock is still hated and extremely cheap. The subscriber churn data still doesn’t fully support the idea that Sirius XM is in an irreversible secular decline.
Here is a snapshot of the monthly churn metrics for Sirius:


The data suggests that SiriusXM’s subscriber base is very sticky. Even going back to Q1 2020, the monthly churn has never gone above 1.8%.
From this investor presentation back in early 2024:
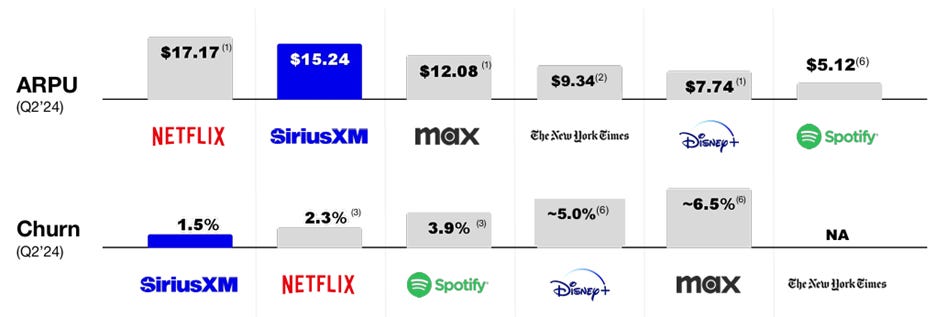
As you can see, SiriusXM has some of the lowest churn (less than half of Spotify) and nearly 3x the average revenue per user (ARPU) that Spotify has!
Importance of Subscription Revenue
SiriusXM generates roughly 75% of its revenue from subscriptions, with only 21% coming from advertising and the remaining 4% from equipment and other sources. This revenue mix is important because subscription revenue is far more resilient and predictable during recessions than ad-based models. When the economy slows, companies slash marketing budgets long before consumers cancel low-cost entertainment services—especially ones used daily during commutes.
This stability gives SiriusXM a built-in buffer during downturns, making its revenue base much “stickier” than pure-play streaming or ad-supported businesses. Despite this, the consensus on Wall Street is that SiriusXM is in a long-term secular decline. But when you dig into the numbers, they paint a far different picture—mainly that SiriusXM has a very sticky subscriber base and is not the “melting ice cube” that some think it is.
Takeaway
At this point, the story is fairly straightforward: SiriusXM continues to throw off enormous amounts of cash, maintains some of the lowest subscriber churn in the industry, and operates with a far more resilient revenue model than most investors appreciate.
The company isn’t priced like a stable subscription business—it’s priced like it’s in structural decline. Yet the numbers continue to show a business that is far more durable than the market sentiment suggests.
With a free cash flow yield approaching 16% in 2025 and potentially near 20% in 2027, investors are essentially being paid to wait while management reduces debt and returns capital to shareholders. The stock has already begun to re-rate from the April lows, but in my view, the gap between perception and reality remains wide. If fundamentals continue to hold, that gap should close over time.